Integrating Virtual Sports Analytics into Traditional Accumulator Payout Frameworks
Drew Butler · Oct 3, 2026
Integrating Virtual Sports Analytics into Traditional Accumulator Payout Frameworks
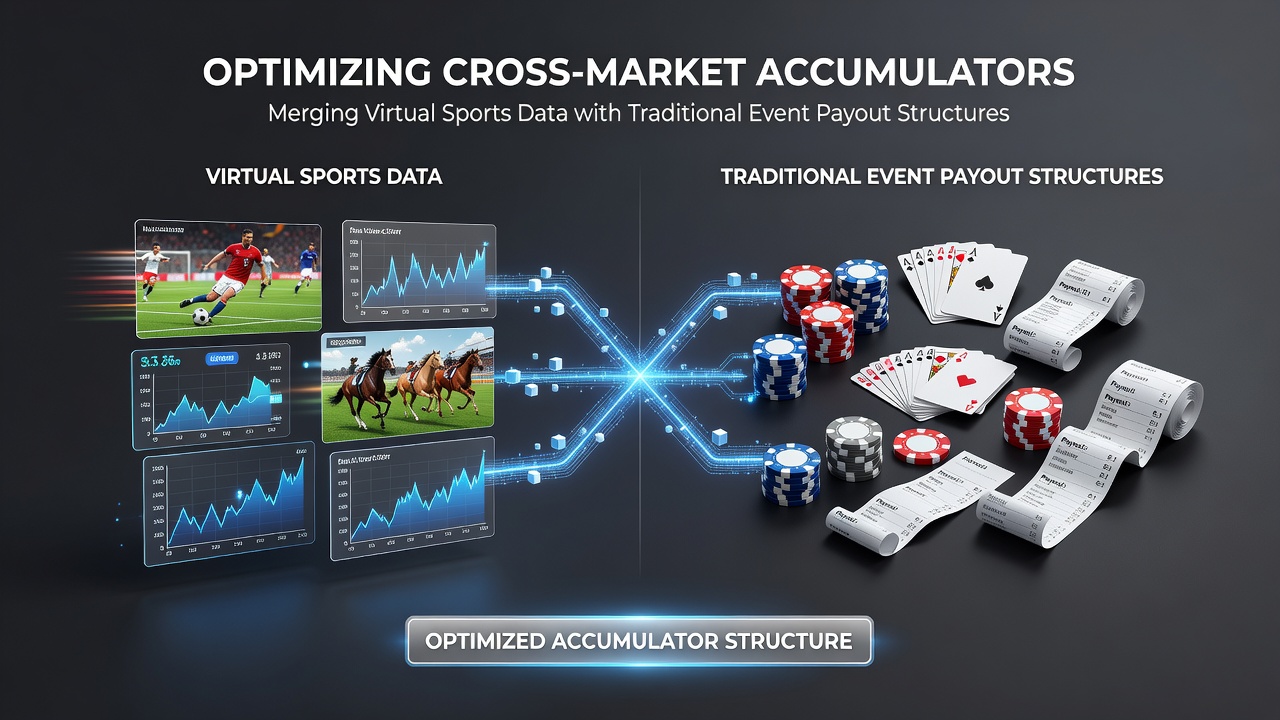
Virtual sports generate continuous streams of outcome data that operators and analysts track through standardized metrics such as win probabilities, scoring distributions, and cycle times, and these figures sit alongside payout tables from live football, tennis, and horse racing events. Observers note that accumulator structures multiply base odds across several legs, which means even small adjustments derived from virtual data can shift overall return profiles when the same bookmaker applies consistent margin rules across both product types.
Virtual Sports Data Sources and Their Core Metrics
Simulated football matches, greyhound races, and tennis tournaments run on fixed algorithms that produce thousands of results each month, and researchers compile frequency tables for goals scored, sets completed, and finishing positions. These tables reveal recurring patterns in variance and volatility that differ from live event distributions yet share structural similarities in how they respond to external variables like time of day or participant sequencing. Data from these simulations feed into models that recalibrate implied probabilities for accumulator legs drawn from real schedules, particularly when traditional markets show thin liquidity or delayed updates.
Operators in multiple jurisdictions publish aggregated performance indicators that cover both virtual and live verticals, allowing cross-referencing without direct regulatory overlap. One study released by the Nevada Gaming Control Board documented how virtual product margins remained stable across quarterly reporting periods while live accumulator volumes fluctuated with major tournament calendars, and analysts used that stability to benchmark risk parameters for combined ticket construction.
Accumulator Payout Mechanics in Conventional Markets
Traditional accumulators calculate returns by chaining decimal or fractional odds, with each leg's multiplier applied sequentially and deductions applied only at settlement. Dead-heat rules, each-way terms, and cash-out formulas introduce additional variables that change net payout when a ticket spans several events. Because virtual sports operate on predetermined cycles, their settlement times can be aligned with live fixtures to create staggered resolution sequences, which in turn affects when operators release funds or adjust remaining legs on open tickets.
Market makers adjust accumulator bonuses according to the number of legs and the perceived correlation between selections, and virtual data supplies an independent correlation matrix that does not rely on historical live results alone. Those matrices help isolate legs where virtual-derived probabilities diverge from live book prices, creating opportunities to balance overall ticket exposure before the first event begins.
Merging Datasets for Cross-Market Construction
Analysts combine virtual outcome logs with live fixture schedules by mapping equivalent statistical categories, such as converting virtual goal distributions into expected goal ranges for real matches. Software platforms ingest both streams through API endpoints and apply weighting factors that reflect the relative sample sizes of each dataset, producing adjusted odds inputs for accumulator builders. When October 2026 fixture lists become available, operators typically preload virtual simulations calibrated against similar past tournaments, which supplies early probability anchors that can be refined as live team news emerges.
Industry reports from the European Gaming and Betting Association indicate that cross-product accumulator volume increased in markets where virtual data feeds were integrated into existing retail terminals, and settlement automation reduced manual reconciliation errors across hybrid tickets. The same reports note that payout structures remained unchanged, yet the underlying probability inputs gained granularity from the additional simulation layer.
Practical Implementation Steps
Operators begin by aligning data schemas so that virtual event timestamps correspond to live market opening windows, then run regression tests on historical accumulator settlements to measure variance reduction. Risk teams set exposure caps that treat virtual-derived legs as separate categories for margin calculations, preventing over-concentration while still allowing the accumulator multiplier to function. Front-end interfaces display combined probability bars that update in real time as virtual cycles complete and live odds shift, giving users a single view of the ticket before confirmation.
Conclusion
Cross-market accumulator optimization rests on consistent data mapping, stable payout rules, and automated settlement pipelines that treat virtual and live inputs as complementary rather than competing sources. As fixture calendars advance into 2026, continued alignment of these datasets supports more granular ticket construction while preserving the structural integrity of accumulator returns across both product lines.